Navigating the Fed's Latest Rate Adjustment
How the recent federal funds rate hike influences your personal savings and borrowing costs.
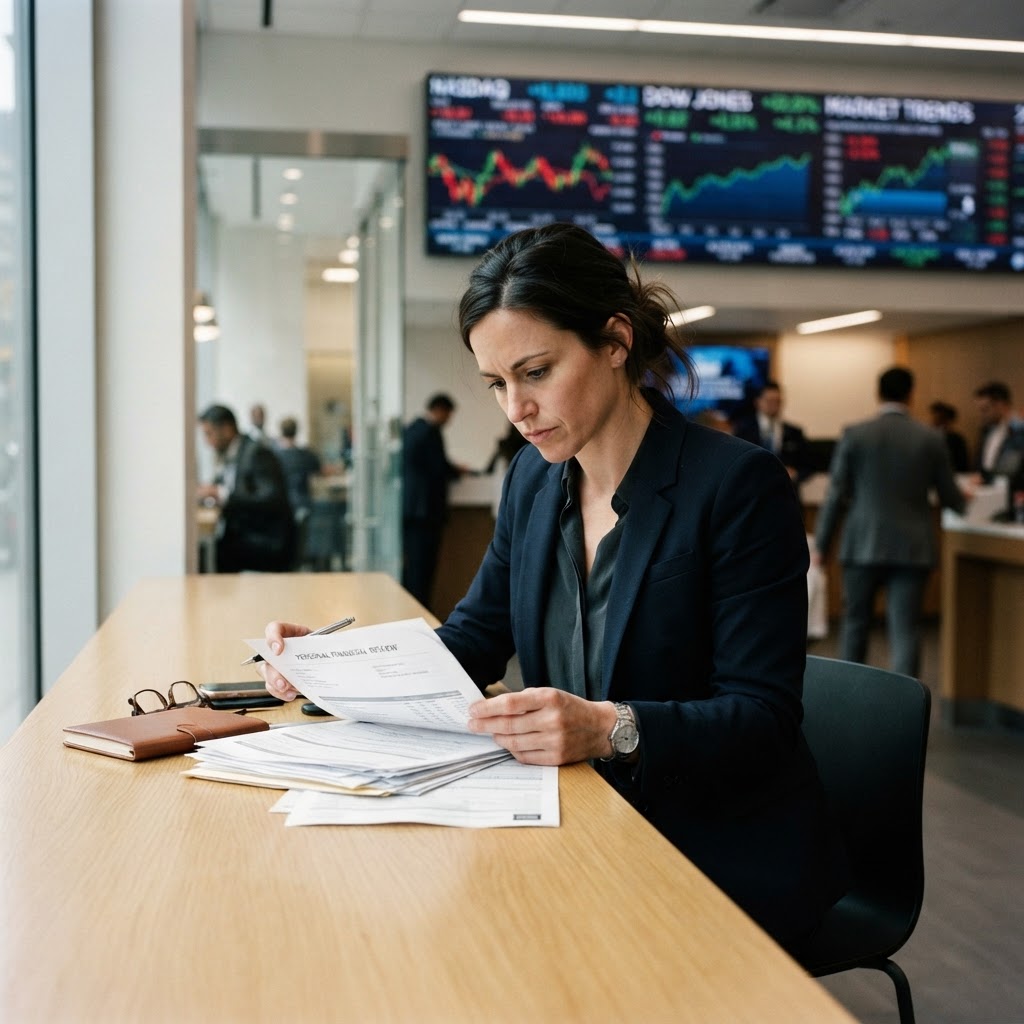
The Federal Reserve recently implemented a quarter-percentage-point increase to the federal funds rate, moving the target range to 3.75%–4.00%. This policy shift, aimed at addressing persistent inflation, serves as a significant signal for the broader financial landscape. While the central bank does not dictate consumer interest rates directly, its decisions ripple through the economy, influencing the costs and returns associated with everyday financial products.
For individuals holding debt, the news presents a more challenging environment. Borrowing costs are expected to rise, particularly for those with variable-rate obligations. Credit card users are likely to see the most immediate impact, as annual percentage rates (APRs) on revolving debt often move in tandem with the Fed’s benchmark adjustments. Consequently, carrying a balance from month to month will become increasingly expensive for many households.
Conversely, the environment is shifting in favor of those who prioritize saving. Savers can anticipate higher returns on various banking products, including high-yield savings accounts and money market accounts. As banks adjust their offerings in response to the Fed’s move, consumers may find that their cash deposits earn more interest than they have in recent years, providing a modest boost to personal savings growth.
It is important to note that the impact on long-term loans, such as mortgages, is less direct. While the federal funds rate influences short-term borrowing, mortgage rates are primarily shaped by long-term market expectations and inflation trends. Therefore, a hike in the benchmark rate does not automatically translate to an identical increase in home loan quotes.
As the economic climate evolves, financial experts suggest that consumers remain proactive. Managing high-interest debt should be a priority, while savers should monitor their bank accounts to ensure they are capturing the improved yields now available. Understanding these dynamics is essential for maintaining financial health in a period of shifting monetary policy.
RELATED DISPATCHES
Corruption Emerges as a Defining and Costly Battleground in 2026 Midterms
14 minutes 52 seconds ago
Federal Judge Blocks Trump Administration Bid to Segregate California Ballots
15 minutes 1 second ago
Federal Criminal Probe Into Alaska Senate Race Intensifies
15 minutes 10 seconds agoDiscussion (0)
No comments yet. Be the first to join the discussion.