Global Oil Market Shifts Toward Surplus as Prices Face Downward Pressure
Rising production from the Middle East and cooling demand are expected to drive crude prices toward $70 by 2027.
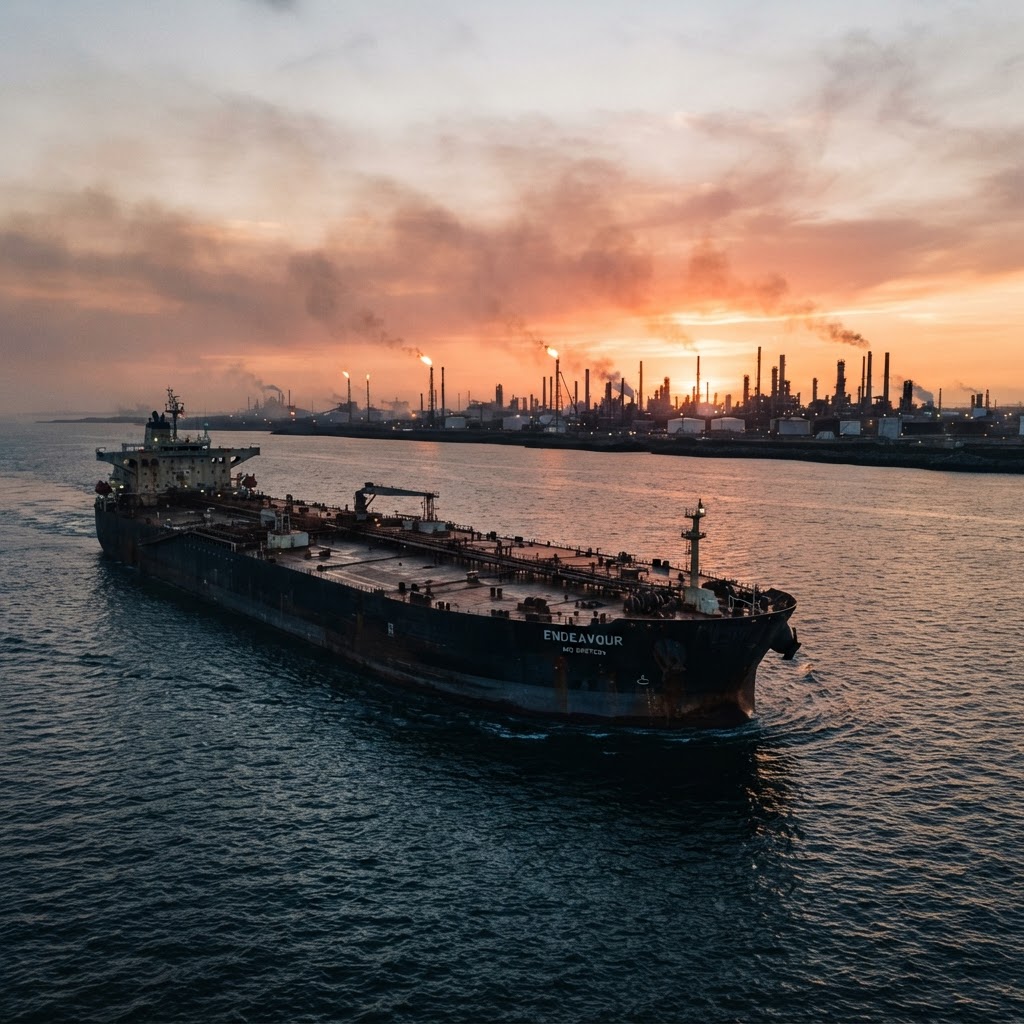
The global energy landscape is undergoing a significant transformation as the oil market transitions from a period of acute scarcity to a projected supply surplus. According to recent data from the International Energy Agency (IEA), a faster-than-anticipated recovery in Middle East crude exports, combined with a softening in global consumption, has effectively reversed earlier forecasts of a year-end deficit. This shift marks a pivotal turning point for the industry, which has grappled with supply disruptions and high price volatility throughout 2026.
Non-OPEC+ production continues to play a critical role in this rebalancing. Nations including the United States, Canada, Brazil, Argentina, and Guyana are significantly boosting their output, providing a stable foundation for global supply growth. This increased production, alongside the gradual restoration of Gulf exports, is expected to push total global supply to approximately 108.1 million barrels per day in 2027, according to IEA projections.
On the demand side, the market is facing headwinds, particularly from China. Economic challenges and the rapid adoption of electric vehicles have led to a notable decline in Chinese fuel consumption. This trend, coupled with the broader impact of high energy prices on global economic activity, has prompted analysts to revise their demand forecasts downward. While a modest recovery in demand is anticipated for 2027, it remains insufficient to absorb the surge in new supply.
Financial institutions and energy agencies are now signaling a downward trajectory for crude prices. With global inventories expected to begin a substantial build-up, analysts at the U.S. Energy Information Administration (EIA) and other major firms anticipate that Brent crude prices could gradually retreat, potentially averaging near $77 per barrel by the final quarter of 2027, with some estimates suggesting even lower levels as the surplus deepens.
Despite this outlook, experts warn that the market remains vulnerable to external shocks. Ongoing geopolitical tensions, persistent attacks on maritime shipping, and infrastructure vulnerabilities continue to pose risks to the supply chain. While the trend toward a surplus is clear, the path to price normalization will likely remain uneven, characterized by continued volatility as the industry navigates the complexities of a shifting global balance.
RELATED DISPATCHES
Discussion (0)
No comments yet. Be the first to join the discussion.