Global Oil Market Shifts to Surplus as Gulf Exports Rebound
The IEA reports that rising production in the Middle East has outpaced demand, signaling a market rebalancing for the final quarter of 2026.
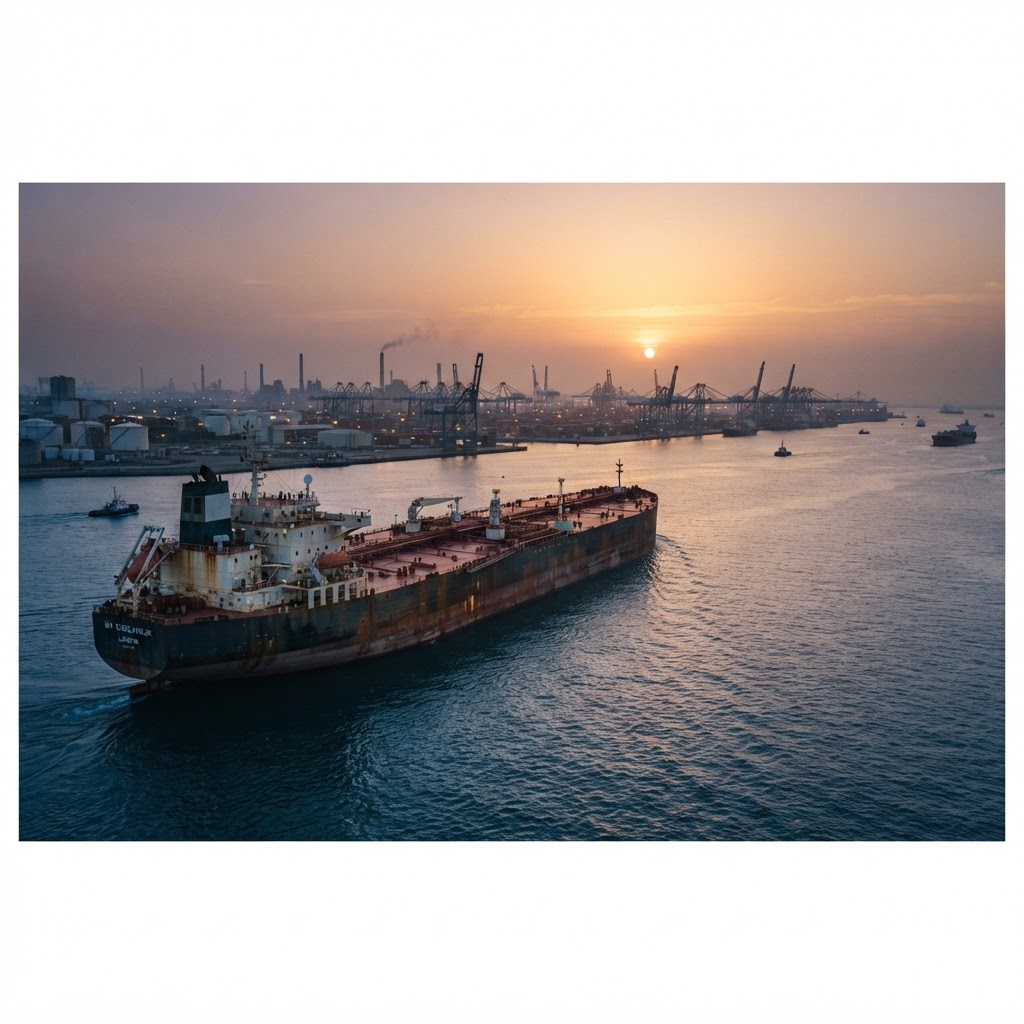
The global oil market is entering a period of supply surplus during the fourth quarter of 2026, according to the latest data from the International Energy Agency (IEA). This shift marks a significant reversal from previous forecasts of a supply deficit, as crude exports from the Gulf region have recovered more rapidly than anticipated despite ongoing security concerns and infrastructure attacks.
In its November report, the IEA noted that global oil production climbed by 2.3 million barrels per day (bpd) in October, reaching 105.4 million bpd. This surge follows a 3 million bpd increase in September, bringing total output growth to 5.3 million bpd since August. The agency has consequently raised its supply estimates for the final quarter of the year by 3.3 million bpd.
Gulf producers have successfully utilized alternative export routes and operational workarounds to bypass shipping disruptions in the Strait of Hormuz. While total exports from the region remain roughly 26% below pre-war levels, crude shipments have seen a robust recovery, reaching 15 million bpd—approximately 82% of their pre-war volume. This influx of supply has been a primary driver in easing market tightness.
Conversely, global oil demand remains under pressure, weighed down by elevated fuel prices and persistent shortages of refined products like diesel. The IEA projects that worldwide demand will contract by 2.7 million bpd throughout 2026, settling at 102.3 million bpd. However, the agency anticipates a return to growth in 2027, forecasting a demand rebound of 2 million bpd as supply chains stabilize and economic conditions improve.
Despite the current surplus, the IEA warned that the market remains vulnerable to downside risks. Ongoing threats to maritime security continue to pose a challenge to a sustained recovery. While crude prices have retreated from their October peaks—dropping significantly from $136 per barrel to approximately $93 per barrel—they remain well above pre-war levels, reflecting the lingering impact of geopolitical instability on the energy sector.
RELATED DISPATCHES
Discussion (0)
No comments yet. Be the first to join the discussion.